Inflation-Proof Budget Checklist: A Monthly Price Plan
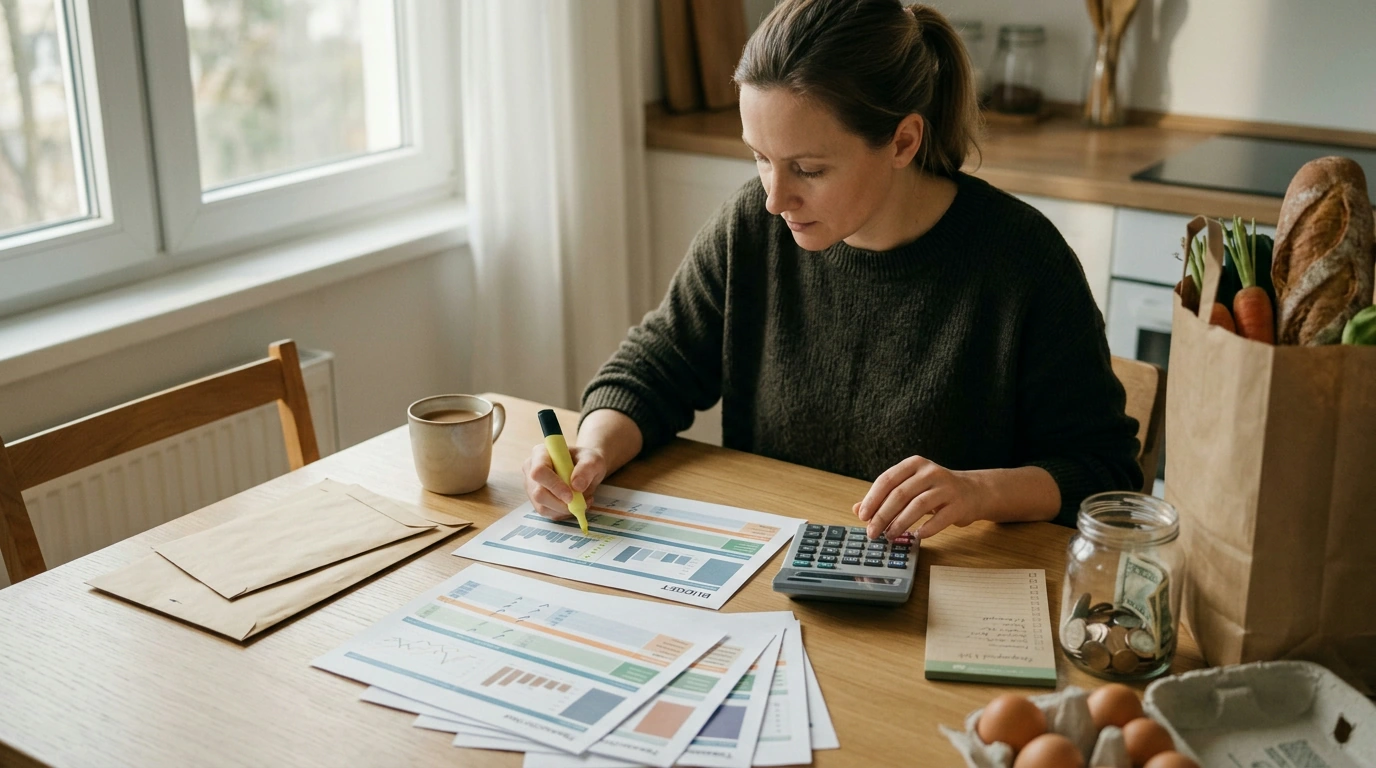
Inflation-Proof Your Wallet Checklist: A Practical, Printable Plan for Rising Prices
When everyday costs climb, the budget that worked last year can quietly stop working. A simple way to regain control is to run a focused checkup: identify which categories are inflating fastest, tighten the leak points, and rebuild spending limits around today’s prices—not last month’s habits. The goal isn’t perfection; it’s creating a repeatable routine that protects essentials, reduces waste, and keeps savings goals alive even when costs rise. The checklist approach below turns inflation into manageable actions you can do in one sitting, then revisit monthly.
Start with a quick inflation checkup (30 minutes)
- Pull the last 60–90 days of transactions and group them into: housing, utilities, groceries, transportation, insurance/medical, debt, subscriptions, and “everything else.”
- Circle categories that changed the most recently (common examples: groceries, car insurance, electricity). These become “high-alert” categories for the next month.
- Write down any price jumps that are permanent (insurance premiums, rent renewal) vs. variable (fuel, produce). Permanent changes should be built into baseline spending limits.
- Set one clear priority order: protect essentials first, then debt minimums, then savings contributions—even if small.
If you want a single-page tool you can run the same way each month, the Inflation-Proof Your Wallet Checklist (printable guide) keeps the steps in one place so you’re not rebuilding the process from scratch every time prices shift.
Rebuild your baseline: needs, true costs, and buffers
- List fixed needs first: rent/mortgage, basic utilities, insurance, minimum debt payments, and essential groceries.
- Convert irregular bills into monthly amounts (car registration, annual subscriptions, semiannual insurance). Treat these as monthly obligations to avoid surprise hits.
- Add a buffer line for inflation volatility (often 2–5% of take-home pay). This reduces the chance of pulling from savings when a bill spikes.
- If income is variable, base the budget on a conservative month and use any extra for catch-up categories, debt, or savings.
Inflation-proof baseline worksheet (example framework)
| Category | Monthly baseline | Inflation pressure | Adjustment action |
|---|---|---|---|
| Groceries | ___ | High/Medium/Low | Swap brands, plan 3 low-cost meals/week, use pantry inventory first |
| Utilities | ___ | High/Medium/Low | Budget to seasonal peak, request level billing, reduce peak-time use |
| Transportation | ___ | High/Medium/Low | Bundle errands, compare fuel prices, revisit insurance quotes |
| Insurance/Medical | ___ | High/Medium/Low | Check deductibles, review plan changes, ask about discounts |
| Subscriptions | ___ | High/Medium/Low | Cancel or pause 1–2 items, switch to annual only if truly used |
Cut costs without feeling deprived: the “swap, shrink, shift” method
- Swap: Replace high-cost versions with lower-cost equivalents (store brands, generic medications, lower-cost data plans).
- Shrink: Keep the category but reduce frequency or quantity (fewer takeout meals, smaller add-on purchases).
- Shift: Move spending to lower-price timing or channels (buy seasonal produce, use pickup to reduce impulse buys, shop midweek markdowns).
- Pick two categories to target for 14 days; small, consistent wins beat a one-time extreme cut that rebounds.
A practical way to make “shrink” stick is to replace out-of-home spending with at-home comfort you actually use. If your budget is leaking through “little treats” and entertainment, improving the at-home setup can reduce the urge to spend elsewhere—like adding a dedicated reading or movie spot with something like the Kids Recliner Chair for low-cost, repeatable downtime.
Lock in wins: renegotiate and reprice the big levers
- Insurance: Compare auto/home/renters rates at renewal; ask your current provider about discounts or re-rating.
- Housing: If moving isn’t realistic, look for smaller levers—utility efficiency, roommates, negotiating fees, or refinancing (when rates and eligibility align).
- Debt: Prioritize high-interest balances; explore hardship programs or rate reductions if payments are getting tight.
- Bills: Ask about level billing for utilities and payment plans for medical bills to avoid late fees and stress spending.
For a reality check on broad price trends, the U.S. Bureau of Labor Statistics Consumer Price Index (CPI) is a solid reference. For household budgeting tools and plain-language guidance, the Consumer Financial Protection Bureau budgeting resources can help you compare approaches and pick a system you’ll keep using.
Make the budget inflation-resistant: rules that update automatically
- Use a “price-update day” once a month: adjust groceries, fuel, and utilities based on recent receipts rather than guesses.
- Create category caps with a default response: when a cap is hit, pause, substitute, or move money from a pre-decided category (not savings).
- Separate sinking funds for predictable future costs (car repairs, gifts, back-to-school). Inflation often shows up first in these irregular expenses.
- Keep a small “opportunity fund” for bulk buys when prices dip, without destabilizing the rest of the budget.
Printable checklist: one page to run every month
If you prefer a ready-to-print layout rather than rewriting these steps in a notes app, the Inflation-Proof Your Wallet Checklist (printable guide) is designed for quick monthly reviews and helps you document the “high-alert” categories you’re watching.
When prices keep rising: what to do if the math still doesn’t work
FAQ
How often should a budget be updated during inflation?
Update variable categories monthly (groceries, fuel, utilities), review fixed bills quarterly, and adjust immediately when rent or insurance rates change. A short monthly “price-update day” keeps your plan aligned with real receipts.
What categories usually increase first when prices rise?
Groceries, utilities, transportation (fuel and repairs), insurance premiums, and subscription price hikes often show it early. Track your top three personal “high-alert” categories because individual spending patterns can differ from national averages.
How can savings continue when essentials cost more?
Keep smaller automated transfers going to maintain the habit, even if the amount drops. Use sinking funds to prevent predictable expenses from turning into emergencies, and redirect money from recurring leakage (fees, unused subscriptions) to rebuild savings over time.

Leave a comment